You have found an Irish business to buy. The seller mentions taking over the company, the broker talks about assets and goodwill, and somebody suggests registering a fresh LTD. These can describe very different transactions. Choose what is being bought and who will buy it before treating incorporation as the first administrative task.
This guide helps prospective owners prepare a formation brief and a transaction-adviser checklist. It is not a recommendation to buy a particular business or a substitute for legal, financial and tax due diligence. Official CRO, Revenue, Workplace Relations Commission and CCPC guidance was checked on 27 October 2026.
Separate the buyer from the thing being bought
An asset purchase and a share purchase describe what changes hands. A new company describes a possible buyer. A new LTD and a share purchase are not mutually exclusive: a newly formed company can be the shareholder buying an existing trading company, subject to the transaction's legal and tax design.
In an asset deal, the agreement identifies the business assets and any liabilities being assumed. In a share deal, the purchaser acquires ownership interests in the company; the company remains the legal person carrying on its business. Section 25 provides for the incorporated body to have perpetual succession, so a change of members is not a fresh incorporation.
Start by writing one sentence identifying the buyer, seller and subject of the purchase. If the seller trades personally rather than through a company, there are no shares in that sole-trader business to buy. Resolve that basic identity question before comparing package prices.
| Possible route | What the buyer acquires |
|---|---|
| New LTD buys assets | The agreed business assets |
| Buyer acquires shares | An interest in the existing company |
| New LTD buys shares | Ownership of the trading company |
Buying assets: specify the operating business, not just the equipment
An asset schedule might include equipment, stock, goodwill, intellectual property and specified contracts. Identify what the seller actually owns, what is financed or leased, what is excluded and which consents are needed. A photograph of machinery and a verbal promise to hand over customers are not an adequate acquisition specification.
Ask the solicitor to check title, security interests, assumed obligations and the transfer mechanism for each important item. An asset agreement can define the commercial allocation of liabilities, but it is not a guarantee that no legal obligations transfer. Employee protections, for example, require a separate assessment.
Do not assume the premises, domain name, software licences, customer data, telephone number or supplier terms move merely because they are used by the business. Prepare a handover list, identify the responsible person for each consent or transfer and establish what must be ready before the new operator starts taking orders.
Buying shares: review the existing company rather than expecting a reset
Changing shareholders does not erase the target company's debts, contracts, filing history or unresolved claims. Those remain matters for the same company. This is not the same as saying the buyer personally becomes liable for every company debt; the risk assessment concerns the entity being acquired and any guarantees or obligations the buyer separately accepts.
CRO makes public company and submission information available through CORE, including status, registration dates and annual-return information. Use it as one part of due diligence, not as a certificate that the business has no liabilities. Obtain current accounts, tax records, bank information, statutory registers, contracts and explanations of disputes through the transaction team.
Continuity can matter commercially, but inspect change-of-control terms rather than assuming every agreement remains unaffected. Ask the solicitor which lender, landlord, customer, licensing or other approvals are needed for the actual structure. A company name or registration date alone does not answer that question.
Example: buying a small harbour-maintenance business
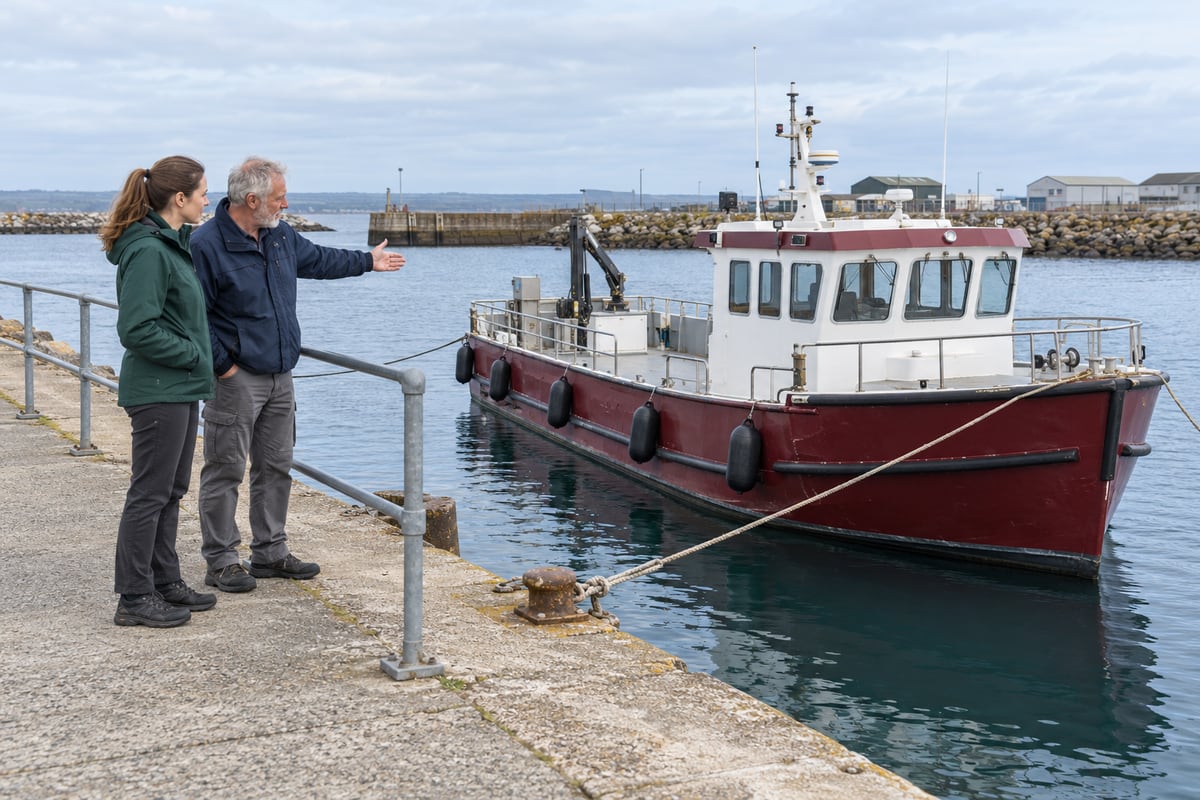
Maya is considering a fictional harbour-maintenance business using a workboat, tools, customer contracts and a small team. If her new LTD buys the agreed assets, it is that LTD which needs the documented rights and arrangements to operate them. The seller's company shares do not transfer simply because the boat and tools are included.
Alternatively, Maya might buy all the shares in the existing trading company. That company would remain the owner of its boat and the party to its agreements, subject to the detailed checks and consents. The company's history would still need review; changing the owner is not a way to create a clean trading record.
A third structure might use Maya's newly formed company to buy those shares. The trading company would then sit beneath a new shareholder. The boat does not automatically become an asset of the new holding company. The advisers should explain the ownership chart, funding and intended employer before anybody drafts formation instructions or promises a completion date.
Employees: a new company does not automatically mean a new employment start
The WRC explains that the Transfer of Undertakings Regulations can apply when a business or part of one moves from one employer to another. Where they apply, existing employment rights and accrued service are protected, with detailed rules and exceptions. Do not plan on resetting service or dismissing staff solely because a new LTD is the buyer.
The WRC also describes information and consultation duties for the employers involved. Have employment advisers assess the proposed transfer and its timetable before announcing new terms. A purchaser's plan to keep only selected assets does not, by itself, settle whether these protections apply.
If a share purchase leaves the same company as the legal employer, distinguish that from moving the business to another employer. Still review contracts, payroll, pensions, accrued leave and outstanding disputes. Ask for a written employee-handover plan rather than relying on the headline description of the deal.
VAT and Stamp Duty need a transaction-specific comparison
Revenue's Transfer of Business relief can treat a qualifying transfer of business assets as not being a supply for VAT purposes. Its conditions concern the recipient and an undertaking, or part of one, capable of independent operation. Calling an agreement a business sale does not establish that those conditions are met.
In the harbour example, buying a boat alone should not be assumed to be a transfer of an independently operable business. Ask the tax adviser to review the entire package and the relevant rules. Revenue's manual also explains that TOB treatment is mandatory where its conditions apply, not simply a tax option the parties select by preference.
Stamp Duty is a separate question. Revenue distinguishes the transfer of existing shares from the issue of new shares, and identifies business-asset agreements among situations requiring particular attention. Have the adviser compare the actual documents, assets, consideration, property interests and any applicable reliefs; do not choose a route from a remembered headline rate.
Agree funding and required approvals before completion
Document where the acquisition money comes from, who borrows, who gives security and what cash the business needs immediately afterwards. Buying the headline assets without enough working capital for wages, stock, insurance and ordinary bills can leave an otherwise promising handover unable to operate.
If target-company money, guarantees or security will support a purchase of shares, have the solicitor examine Section 82's financial-assistance rules and any applicable exception or procedure. A new holding company does not itself remove those restrictions. Do not move funds on an assumption that ownership makes every account interchangeable.
Regulatory review is another separate workstream. The CCPC's acquisition definition can include assets constituting a business, and its guidance covers notification and below-threshold call-in powers. Ask the transaction advisers to check current requirements and sector permissions before completion. Incorporation is not clearance to implement a transaction.
When to form the buyer and arrange tax registration
Once the advisers have chosen the buyer structure, give the formation team the agreed owners, share allocation, officers, activity and address plan. Explain whether the company will operate the acquired business or hold shares in another company. The company documents should match that intended role.
Do not casually sign a binding purchase agreement for a company that does not yet exist. Section 45 deals with pre-incorporation transactions and provides for personal binding effect before ratification, absent express agreement to the contrary. Have the solicitor arrange the correct buyer, signing and timing rather than assuming a later certificate fixes every earlier commitment.
Revenue gives a registered company its own Tax Reference Number. For a new operating LTD, plan the relevant registrations, invoices and payroll handover; do not reuse the seller's numbers as though the legal person had not changed. In a share deal, review and update the continuing company's arrangements instead of treating it as automatically newly registered.
Keep the completion records separate from routine CRO changes
CRO says a stock transfer form is not a CRO form and should not be filed there. Share transfers are reflected in the next annual return, while a Stamp Duty return is filed with Revenue if the transfer instrument is chargeable. That reporting distinction does not replace a properly completed share acquisition or the company's ownership records.
A director, secretary, address or name change is a different task from acquiring the shares. Agree the completion record pack and subsequent filings with the solicitor and filing provider. Include any beneficial-ownership updates that the actual ownership change requires, rather than assuming one CRO form updates every register.
Checklist before requesting formation support
Prepare a short non-confidential brief for the formation enquiry, while sharing the seller's private records through the secure process agreed with the transaction advisers. Identify the unresolved decisions instead of making a new company application look settled when the buyer structure is still being negotiated.
- Identify the actual seller and whether it trades personally or through a company.
- State whether assets, shares or a combination will be acquired.
- Confirm the intended buyer and any holding-company structure with advisers.
- List assets, contracts, premises and permissions needing review or consent.
- Arrange financial, tax, legal and employment due diligence.
- Agree the funding, security, working-capital plan and necessary approvals.
- Choose the formation details and realistic signing and completion timetable.
- Assign tax registrations, operational handover, ownership records and post-completion filings.
What StartCompany.ie formation does and does not cover
StartCompany.ie provides the services listed in its Irish LTD formation packages. Compare the current packages once the proposed new company's purpose and owners are clear. Explain any corporate shareholder, overseas director or address requirement before ordering so the appropriate route can be identified.
Incorporation is not acquisition due diligence. A package's formation documents, basic advice or listed company changes are not a substitute for a negotiated purchase agreement, tax-structure opinion, employee-transfer assessment, financing approval or review of the seller's liabilities. Confirm those workstreams with the appropriate advisers.
Agree the formation deliverables, any additional services and total payable separately from the cost of buying the business. A new registration does not guarantee banking, tax treatment, licence transfer, immigration permission or a safe investment. If the transaction structure is not settled, contact us about the formation brief before purchasing a package.
StartCompany.ie service
New Irish Company Formation
Official information and next steps
Official guidance and the relevant revised legislation were checked on 27 October 2026. This is a buyer-preparation guide, not transaction-specific legal, tax, employment, valuation or investment advice. Review current rules and the actual documents with the advisers handling the acquisition before committing funds or signing.
- Companies Act: Section 25, corporate continuity
- CRO: public company and submission records
- WRC: Transfer of Undertakings Regulations
- Revenue: Transfer of Business relief overview
- Revenue: Transfer of Business manual
- Revenue: Stamp Duty on shares and new issues
- Revenue: non-residential property and business-asset agreements
- Companies Act: Section 82, financial assistance
- CCPC: merger and acquisition notification
- Companies Act: Section 45, pre-incorporation transactions
- Revenue: business registration and company tax identity
- CRO: stock and share transfers