
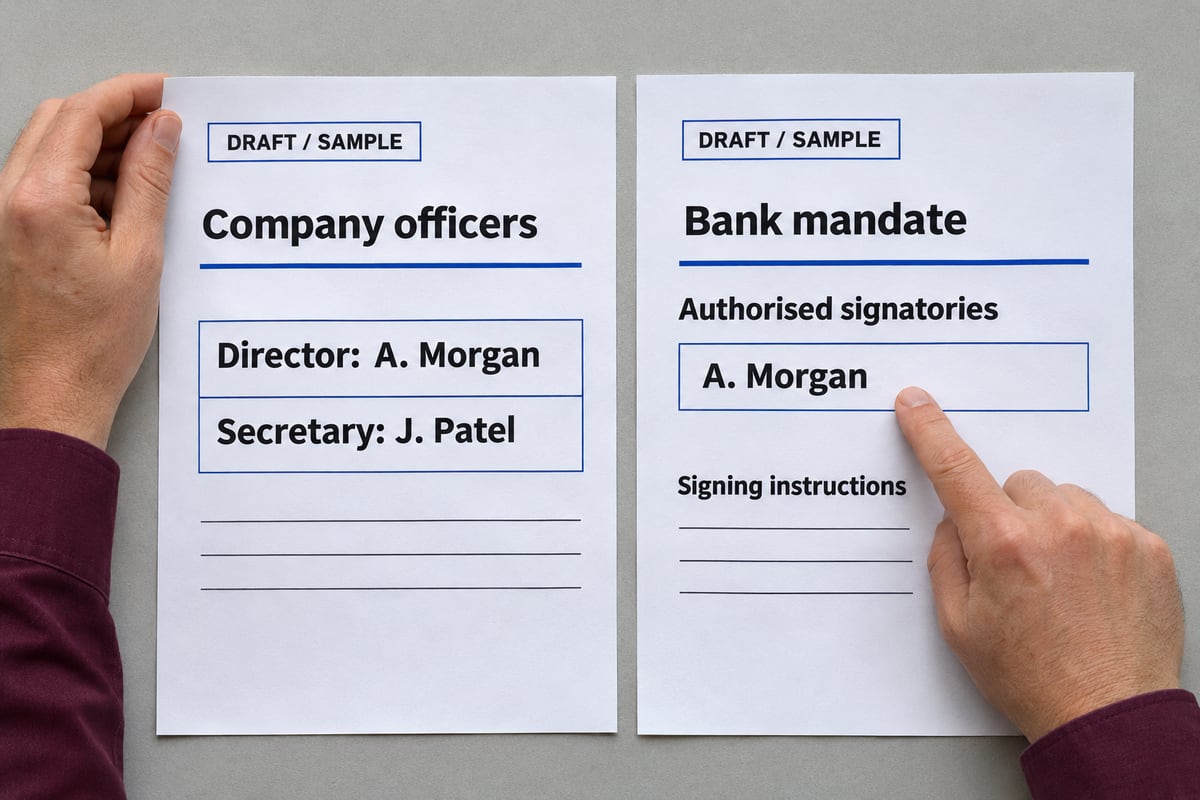
You need a separate secretary for your Irish LTD, but you do not want to give an outside provider control of its money. Does naming a professional company secretary also let them log in, see balances or authorise transfers? Those are sensible questions to settle before ordering an appointment.
This guide separates the company office from banking authority and shows what to check in an engagement, resolution and bank setup. It is not a bank recommendation, a mandate template or advice on a disputed transaction. Your company's documents and the bank's current requirements need their own review.
1. The secretary office is real, but it is not a banking permission
Section 129 of the Companies Act 2014 requires a secretary and provides for appointment by the directors. It also prevents a sole director from being that company's secretary. For a one-director LTD, appointing somebody else addresses that company-law requirement; it does not answer who should operate the bank account.
Under section 226, the secretary's duties include those delegated by the board, without removing duties arising under legislation or other law. A professional or nominee appointment is therefore a real office, not a promise to lend a name while ignoring responsibilities.
Agree the working scope in writing. Statutory-record guidance, reminders and officer-filing assistance are different from administering a bank profile or approving payments. Do not assume either that all financial access is included or that the secretary can never receive financial information needed for agreed duties.
2. Separate four records before asking who has access
A name appearing in company officer records is not the same as that name appearing on the bank's operating instructions. Bank of Ireland describes its mandate as identifying who can operate the account and the applicable signing instructions. Its change process includes checks and confirmation when the replacement mandate is in place.
Ask the bank for the current position, not just the application your company intended to submit. A draft, a board decision and a bank-implemented change are different stages. This comparison helps you identify the missing evidence.
| Record or role | What to establish |
|---|---|
| Secretary appointment | Who holds the office and the agreed duties. |
| Board authority | What the company has authorised, and for whom. |
| Bank mandate | Named operators and signing instructions accepted by the bank. |
| Online permissions | Users, account visibility, payment rights and administrators. |
3. Directors should decide authority deliberately
Section 158 places management of the company's business with its directors, subject to the Act, constitution and relevant member directions. It also allows delegation. Use that distinction when deciding whether an external secretary needs any authority beyond the statutory role and agreed administrative work.
Record the proposed person's exact role, the task, any limits and the intended approval process. If the company does not want the secretary operating its account, say so in the engagement and check that the banking documents and actual settings reflect that decision.
Do not treat an internal restriction as a complete answer to every question about third-party authority. Express delegations, the company's conduct, documents and legal rules can matter. Obtain legal advice where borrowing, guarantees, disputed authority or an unusual mandate is involved. Our separate contract-signing guide explains why signing capacity deserves its own review.
4. A secretary signing banking paperwork needs to read its effect
A bank may ask for a certified company resolution as part of its paperwork. Do not assume that every signature on a banking pack means the signer is a payment operator, but do not dismiss it as harmless administration either.
For example, Bank of Ireland's published limited-company mandate has sections for authorised signatories and signing instructions, plus a separate confirmation certifying the resolution. That confirmation can involve a director or secretary. The pack also contains substantive banking authorisations. These are different functions within one document.
Before anyone signs, identify the capacity in which they sign, every person named elsewhere and the authority the resolution grants. Ask the bank to explain uncertain requirements for your company structure. Never sign an incomplete pack on an assurance that somebody will fill in the permissions later. This is a provider-specific example, not a universal signature rule for every Irish bank.
5. Online administrator access is not the same as payment access
Banking products can separate administrative controls from day-to-day account use. Bank of Ireland's Business On Line guidance says administrators manage users, access levels and authorisation limits. An administrator needs a separate user profile to view accounts or make payments.
That does not make administrator access unimportant: controlling users and limits is itself a significant responsibility. The same guidance describes user groups governing account visibility and payment permissions. Ask which roles actually exist in your chosen product rather than assuming every business account offers identical controls.
Discuss viewing balances, downloading statements, creating payees, preparing payments, approving them and changing users separately. Ask whether dual approval and suitable limits are available, how they work and who can change them. Do not assume a paper two-signature instruction automatically produces two approvals in every online channel. Get the bank to confirm the arrangement across the channels you use.
6. Give information securely without sharing your banking identity
A request for a company document, an appointment detail or a statement is not automatically a request to become an online banking user. Ask what information is needed, for which task, who receives it and how it should be delivered. Supply relevant records through an agreed secure route rather than handing over your login.
Do not share personal passwords, PINs or one-time approval codes with a secretary, accountant or support contact. Bank of Ireland's Business On Line security guidance warns against giving Approve app codes to anyone, including people claiming to be bank staff. An ordinary service enquiry is not a place to upload credentials or banking records.
Where continuing access is genuinely necessary and agreed, ask the bank about an appropriate separately authorised setup. Retain a record of the intended scope and review it when the work changes. Do not use another person's credentials as a shortcut around the bank's access process.
7. Example: a sole director appoints an external secretary
Imagine a fictional consultant forming a one-director Irish LTD. The founder chooses a professional secretary for the statutory appointment and records support. The engagement does not authorise the provider to operate the company bank account. The founder remains the proposed banking operator, subject to the bank accepting the setup.
A bank pack later requests company details and resolution certification. The founder sends the complete draft for an agreed review instead of adding the secretary to every named-person field. They check separately which signatures certify the resolution and which entries appoint signatories or online users.
If the bank needs clarification, they obtain it before signing. The outcome is not assumed from the service label. Buying the secretary appointment neither guarantees bank acceptance nor supplies a director, banking licence, tax result or immigration permission. A different company's delegated authority could produce a different arrangement.
8. Replacing the secretary does not finish a banking handover
CRO guidance requires notification of changes to company officer details on Form B10 within 14 days. That company-register process should not be confused with updating the bank. Check whether the outgoing person ever held separate signatory, online-user, administrator or contact roles.
Bank of Ireland publishes a separate process for Business On Line administrator changes, including authorising account holders and bank confirmation. It also distinguishes mandate changes from changes to the online profile. Other providers have their own procedures, so ask yours which actions are required.
Keep a handover list covering each role, the request date, implementation confirmation and any outstanding document access. Do not assume a B10 removes online banking access. If you suspect unauthorised activity, contact the bank immediately through its verified support route rather than waiting for a routine secretary-change filing.
9. Buy a secretary appointment with a clear scope
StartCompany.ie's Company Secretary Service Ireland page describes a 12-month nominee secretary engagement, compliance reminders, officer-filing guidance and statutory-record guidance. It supports sole-director and non-resident founders. Renewal is arranged separately rather than created as an automatic subscription at checkout.
Do not assume the appointment includes bank-account management, payment approval or completion of every bank's documents. If you need a particular certification or signing arrangement, ask whether it can be supported before ordering and agree the scope and total payable.
Annual-return preparation, a registered office and a separate change-of-secretary filing are not automatically included. Check what your formation package already provides to avoid buying the same appointment twice. Where the concern is disputed authority or the legal effect of a banking resolution, obtain appropriate legal advice rather than treating a standard secretary service as transaction advice.
10. Your pre-appointment banking checklist
Use this checklist for a focused discussion with the proposed secretary and bank. You do not need to give a provider your bank password to explain the company structure or ask about appointment scope. Keep private documents out of a general contact form and agree a suitable route if a detailed review is available.
The practical objective is a consistent record: what directors authorised, what the engagement covers, what the bank accepted and what users can actually do. Revisit it after staff, provider or banking-product changes rather than assuming the incorporation paperwork remains the complete answer.
- Identify the legal secretary appointee and the agreed statutory support.
- Record whether any banking task or authority is intended at all.
- Check the complete resolution and every named signatory before signing.
- Confirm the bank's accepted mandate and operating instructions.
- Review online users, account visibility, payment rights and administrator powers.
- Ask how limits and any dual-approval controls operate in each channel.
- Agree secure information delivery without sharing passwords, PINs or codes.
- Plan role-by-role removal and obtain bank confirmation when an engagement ends.
StartCompany.ie service
Company Secretary Service Ireland
Official information and next steps
Checked against the following legislation, CRO guidance and Bank of Ireland's Republic of Ireland business material on 3 November 2026. Banking examples are provider- and product-specific, not a rule for every Irish bank. Forms and access controls can change; confirm current requirements directly. This guide is general information, not legal advice or approval of a particular banking arrangement.
- Companies Act 2014, section 129: appointment and sole-director restriction
- Companies Act 2014, section 226: secretary duties and delegation
- Companies Act 2014, section 158: management and delegated powers
- CRO: company officers and changes to officer details
- Bank of Ireland: business account mandate and change confirmation
- Bank of Ireland: limited-company mandate, signing instructions and resolution certification
- Bank of Ireland: Business On Line administrators, users and access levels
- Bank of Ireland: Business On Line support and approval-code warnings
- Bank of Ireland: changing Business On Line administrators and profile details