
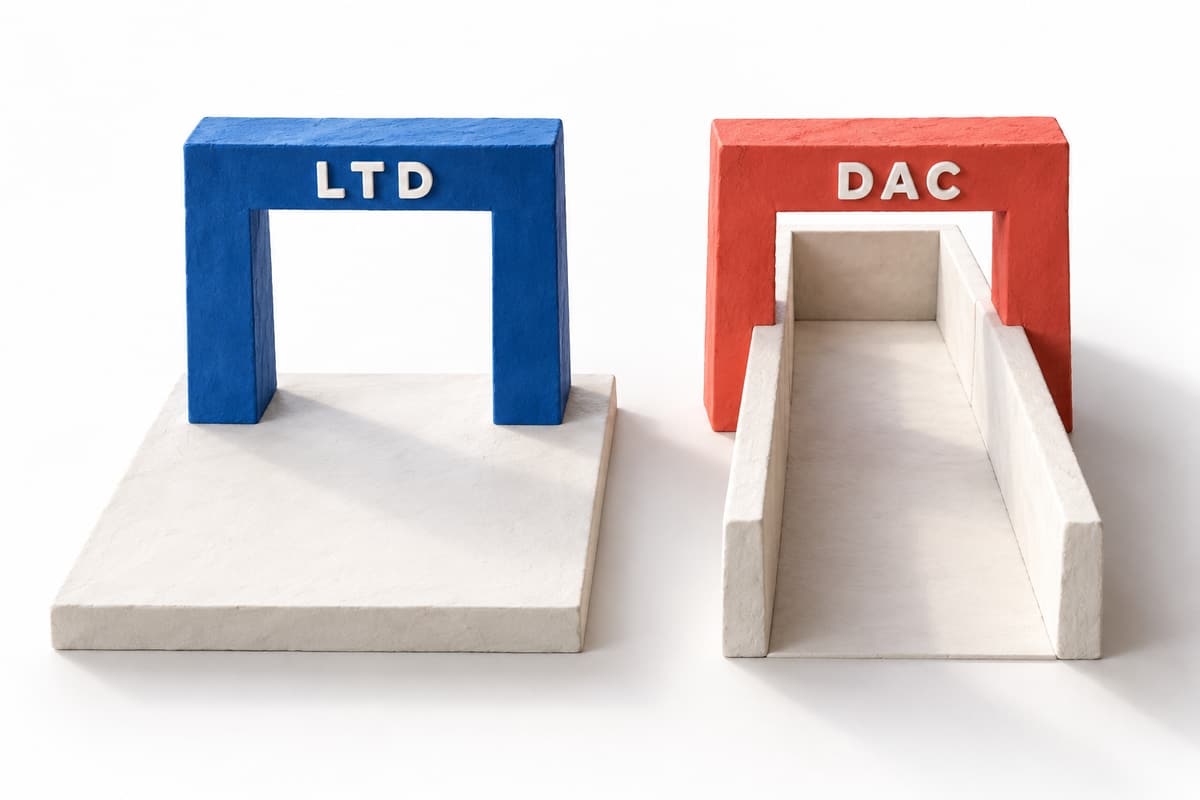
You have decided to incorporate in Ireland, but a bank, co-founder or adviser mentions a Designated Activity Company. Is a DAC a more professional version of an LTD, or does choosing one create work your startup does not need?
The useful distinction is purpose and governance, not prestige. This guide compares an ordinary private company limited by shares with a DAC limited by shares. It does not cover every guarantee, public or regulated structure. Official sources were checked on 24 October 2026. Obtain advice where an investor, regulator, lender or specific project imposes requirements.
Start with the reason someone is asking for a DAC
Ask the person recommending a DAC to identify the actual requirement. Is it in a proposed finance agreement, joint-venture term sheet, regulatory condition or legal opinion? A specific written requirement deserves review. A general comment that a DAC is 'better for investment' is not enough to decide the company type.
For example, a project sponsor may want the company's constitutional purpose tied to an agreed development. Another founder may simply be comparing abbreviations found on large businesses' websites. Those are different decision problems. Describe the business, ownership and proposed obligations to an Irish solicitor before selecting a specialised structure.
Both forms can have shareholders and limited liability. Neither name ending is a quality badge or evidence that a business is financially stronger. This is a choice about the entity's legal framework, not a shortcut to credibility with customers.
| LTD | DAC limited by shares |
|---|---|
| No stated objects | Stated objects |
| May have one director | At least two directors |
| One-document constitution | Memorandum and articles |
| AGM waiver route available | No waiver with 2+ members |
Understand what broad LTD capacity actually means
Section 38 gives an LTD broad capacity to carry on business and enter transactions. Its constitution does not set out a list of objects in the way a DAC's memorandum does. This can be useful when a small company expects its products, markets or delivery model to evolve.
Imagine two founders starting a software service, then adding training and implementation support. They should still check contracts, tax, insurance and any regulated activity, but an LTD does not need a DAC-style objects list simply to describe each new revenue stream.
Broad capacity is not permission to ignore other law. Section 38 expressly preserves legal duties and obligations. Incorporation does not authorise a financial service, grant a professional licence, transfer somebody else's intellectual property or allow work contrary to immigration conditions. Nor does it override restrictions agreed with investors or lenders.
Treat a DAC's objects as a governance decision, not marketing copy
A DAC's memorandum states the objects for which it exists. Section 972 addresses that capacity, including acts that are incidental to attaining the stated objects. Have the proposed wording drafted around the real project and related activities rather than copying an unrelated company's constitution.
Discuss the boundaries before incorporation. Does the business need to own assets, borrow, give security, engage suppliers or provide related services? Who should approve a change in direction? The answer should reflect the parties' intended controls, not an indiscriminate list of every activity imaginable.
There is an important qualification: an act outside the objects is not automatically invalid against a third party. Section 973 protects the validity of DAC acts while preserving directors' obligations to observe the limitations. Do not assume an objects clause makes an unwanted contract disappear or replaces careful authority and contract checks.
Count real directors, not just names on a form
An LTD can have one director. If it does, a separate person must act as secretary. A DAC requires at least two directors. The second appointment is a substantive role, not an administrative signature that a relative or colleague should accept without understanding it.
Map the intended board before choosing the type. Who makes decisions, receives information and has time to perform the role? If two founders will be shareholders, that does not itself appoint both as directors. Equally, a second director does not automatically acquire shares.
Check eligibility, consent, identity requirements and the applicable EEA-resident-director rule or statutory alternative separately. A DAC's two-director requirement does not mean that appointing any two people resolves residence or compliance. The formation provider needs the actual officer structure, not a plan to find a suitable person after filing.
Plan shareholder meetings rather than assuming either type is paperwork-free
An LTD may dispense with an AGM for a particular year using the statutory written resolution signed by all members entitled to attend and vote. Section 175 includes acknowledgement of the financial statements, the business that would have been resolved and the required auditor position. It is not a permanent exemption created by writing 'no AGM' in an informal note.
Section 988 prevents a DAC with more than one member from using that dispensing route. For a two-shareholder DAC, plan for its AGM obligations as part of annual governance. A single-member DAC needs its own assessment; do not apply the two-or-more-member rule without checking the facts.
Neither arrangement removes accounting records, statutory registers, CRO annual returns or applicable tax filings. Meeting administration is one part of ongoing compliance. Ask who will prepare notices, resolutions and minutes, and whether that work is included in the company secretary or accounting engagement.
Do not use the company type to promise a tax or banking outcome
A constitutional choice does not decide whether profits are trading income, whether VAT registration is required or where a company is tax resident. Have those questions assessed from the planned business and management arrangements. Do not choose a DAC because somebody informally promises it pays less tax.
Bank and payment-provider onboarding also remains separate. Prepare an intelligible ownership structure, activity description and funding story. A DAC label does not remove identity checks, guarantee an account or make an unexplained ownership chain acceptable.
Limited liability should also be read accurately. CRO describes a shareholder's exposure on winding up by reference to amounts unpaid on shares. Personal guarantees and a director's own conduct can create separate exposure. Choosing between two limited forms does not make a requested guarantee harmless.
Use a short decision brief for three common situations
First, consider a sole founder opening a straightforward online consultancy with no external investment conditions. An LTD may be a practical starting point, provided the actual activity is lawful and the separate secretary and other requirements are covered. There is no reason to add a second director merely to make the business look larger.
Second, consider two businesses negotiating a tightly defined joint venture. Their solicitor should compare the objects, board controls, reserved decisions and shareholder agreement with the commercial term sheet. A DAC may be appropriate if defined capacity is genuinely part of the design, but joint-venture status alone is not a universal instruction to use one.
Third, consider a regulated or specialist finance project. Start with advice on the required legal form and authorisation, not an ordinary formation checkout. These examples are decision prompts, not eligibility opinions. Keep a written record of why the chosen type serves the venture.
Changing the suffix later is not the same as changing company type
If circumstances change, re-registration may be possible, but it is a formal process. CRO describes Form D20, the relevant resolution, a compliant replacement constitution and additional requirements for the particular route. A company name change alone does not turn an LTD into a DAC.
An LTD moving to another type may need a second director and stated objects. Existing rights, obligations and agreements must be reviewed as part of the change. Do not assume you can cure an investor's structural requirement overnight by editing website text or asking for a new certificate.
Compare the cost of settling the structure now with a later legal and administrative project. That does not mean every possible future investor should dictate today's company. It means identifying requirements that are already known and obtaining advice where they materially affect the decision.
Order the formation route that has actually been agreed
StartCompany.ie's published formation packages are for Irish LTD formation. Do not treat a listed package as a quote for bespoke DAC documents or specialist regulatory work. If a DAC may be needed, ask about suitability and available support before purchasing.
For an agreed LTD, compare the current inclusions and total payable on the pricing page. Identify the registered office, secretary, identity requirements, share structure and first-year support actually needed. Bespoke shareholder agreements, investment negotiations and licensing advice are separate matters unless expressly included.
Bring the provider a concise structure brief rather than an incomplete name and payment. Accurate inputs allow the incorporation documents to reflect the company the founders intend to run.
- Describe the trade, expected changes and any regulated activity.
- Obtain the written basis for any DAC requirement.
- Agree directors, secretary, ownership and decision controls.
- Review the constitution and any shareholder or finance terms together.
- Assign responsibility for meetings, records and annual filings.
- Confirm company type, service scope and total payable before ordering.
StartCompany.ie service
Irish Company Formation Packages
Official information and next steps
Official company-law sources checked on 24 October 2026. This comparison is for an LTD and a DAC limited by shares, not a legal recommendation for a regulated or bespoke structure.
- CRO: company types and LTD/DAC comparison
- Companies Act: Section 38, LTD capacity and continuing legal duties
- Companies Act: Section 972, the objects of a DAC
- Companies Act: Section 973, DAC acts and directors' obligations
- Companies Act: Section 128, LTD director minimum
- Companies Act: Section 175, annual meetings and written resolutions
- Companies Act: Section 988, DACs with more than one member
- CRO: changing company type through re-registration
- CRO: incorporation requirements and company structures