You have agreed an accounting quote for your Irish company, but the accountant says they cannot yet see its tax record. Should you send your ROS password, sign a letter or look for a request online? The right answer depends on the company's Revenue registration and online-access position.
This guide covers the practical customer side of appointing a tax agent: reviewing a ROS link request, checking the requested tax work and resolving an incomplete connection. It is not a guide to changing accountants generally, recovering credentials or registering every tax type. Use it alongside the proposed adviser's onboarding instructions and Revenue's current guidance.
1. Identify the taxpayer and the work before requesting access
Start with the company as a separate taxpayer. Write down the registered name and ask which company tax reference the adviser requires through their secure onboarding channel. Do not substitute the CRO number, a director's PPSN or the reference for an older sole-trader business because it is the number most readily available.
List the work being commissioned: Corporation Tax, VAT where applicable, employer payroll or something else. Keep each director's personal tax engagement separate. For example, preparing the company's CT1 does not mean the same firm has agreed to prepare the director's Form 11. Ask whose record each authorisation concerns and which periods the engagement covers.
Revenue's business guidance says you must notify Revenue if you want an agent to access your tax record. Hiring an accountant and arranging that access are therefore separate onboarding tasks. Put a named company contact against the approval task so that the request does not sit unnoticed while everyone assumes somebody else is dealing with it.
2. Find and review the request in ROS
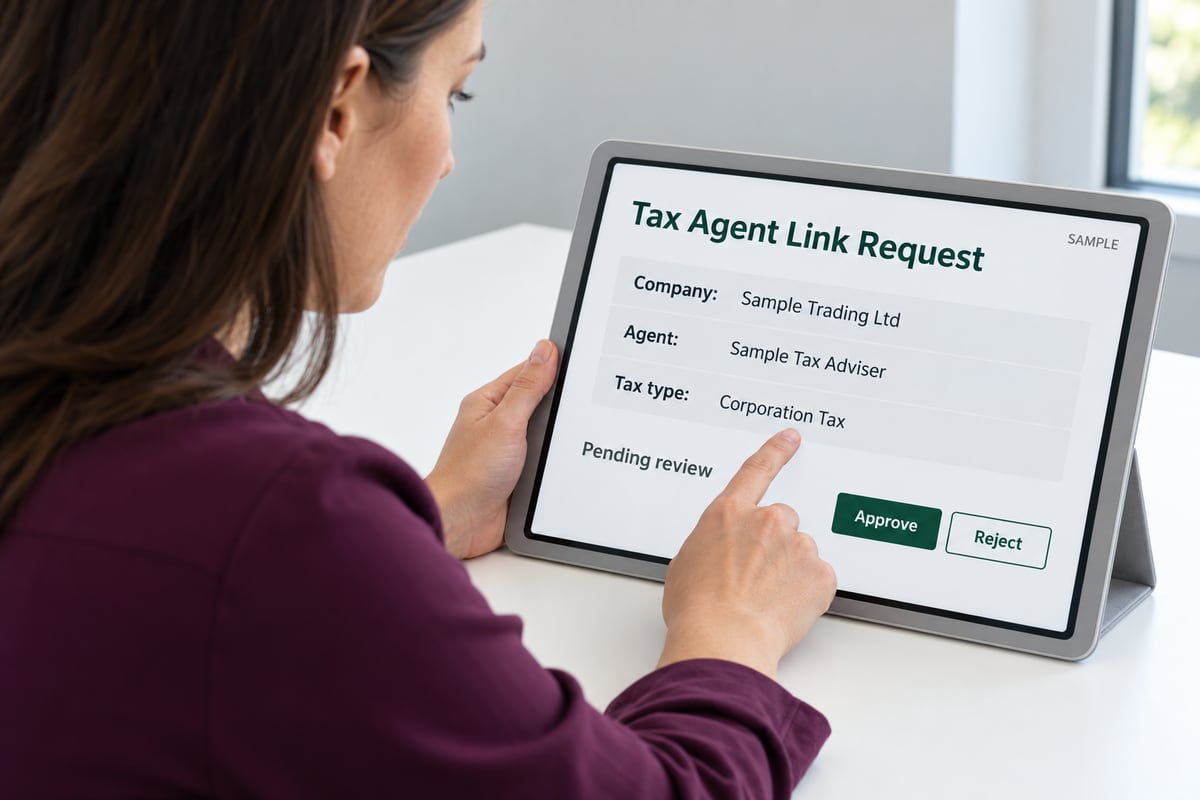
Revenue's current customer instructions say to log into ROS, open Revenue Record and select the inbox document labelled Agent-Link Approval. Review the request details before choosing whether to approve or reject. Alternatively, Other Services contains Manage Agent Link Requests. An email notification alerts you to correspondence; it is not itself your approval.
For this company task, check that you are viewing the company's record. Revenue also publishes a myAccount route for relevant individual customers; it is not a reason to approve a director's personal request as a substitute for company access. If the request seems to concern the wrong taxpayer, stop and clarify it with the adviser.
The current public instructions were published on 12 October 2026. Use the linked Revenue page for its walkthrough and videos rather than an old screenshot forwarded between businesses. If labels or available options differ on your account, describe the difference to the adviser or Revenue support; do not experiment with unrelated registration actions.
3. Check the agent and the requested tax type
Revenue's Agent Link Manager displays the agent name, TAIN, tax registration type and action deadline. Match these to the adviser you engaged. If a firm's public brand differs from the name on the request, obtain an explanation through a contact you already trust. A familiar-looking name alone is not enough to resolve a mismatch.
Use a small task map such as the fictional example below. The point is to check the relationship between the requested link and the agreed assignment, not to insist that every company needs every tax registration. Ask about any extra request before accepting it, and confirm whether another provider already handles that work.
Do not assume one approved tax-head link covers every service. Nor does approving access instruct a provider to prepare every historic return. Record the agreed scope beside the access check so a technical connection is not mistaken for a wider engagement.
| Agreed work | Question to resolve |
|---|---|
| Company CT1 | Is this the company's Corporation Tax link? |
| Company payroll | Who needs employer PAYE access? |
| Company VAT returns | Is VAT work included and the link appropriate? |
| Director Form 11 | Is a separate personal engagement needed? |
4. Distinguish pending, approved and usable access
Revenue's March 2026 e-linking manual says pending requests expire after 30 days. Once expired, they cannot be approved; ask the agent to resubmit. A request rejected in error also needs resubmission. Check the actual status and deadline rather than repeatedly opening an old notification.
The manual's customer approval acknowledgement says the link becomes active within two working days. This is not an immediate-access guarantee. Ask the agent to confirm usable access before relying on it for an imminent filing. Keep the approval confirmation; it is not a tax-return receipt.
For example, a fictional company approves Corporation Tax access but still has incomplete bookkeeping. Its director should track access confirmation, record delivery, draft review and return submission as separate milestones. Marking the first one complete should not cause the other tasks to disappear from the filing plan.
5. If you cannot find the request, diagnose the gap
Ask the agent whether the request was actually submitted, for which taxpayer and tax type, and what status they see. Saying that onboarding has started is not the same as confirming that a request has been sent. Compare the submission details with the company's own record, using secure channels for references.
If an email notification is missing, check Manage Agent Link Requests directly through ROS using Revenue's published route. Also confirm which company colleague controls the relevant access and monitors correspondence. Do not create several duplicate requests simply because one person has not checked the correct record.
If you cannot log into ROS, use Revenue's official recovery or support process. Do not disable security controls, install an unfamiliar remote-access tool or hand over credentials to get around the problem. Explain any approaching filing date to the adviser immediately and agree a contingency; unresolved onboarding is not a completed filing.
6. No ROS registration is a different case from a forgotten login
Revenue's business guidance provides an Agent Link Notification route where the customer is not registered for ROS or myAccount. It requires the taxpayer's tax reference and the agent's TAIN. Have the adviser establish the correct route for this company before asking you to execute a particular form.
A newly incorporated company, an existing company with online access and a company whose contact has lost access are not interchangeable cases. Explain what already exists and what is missing. Do not describe the company as unregistered merely because the director cannot find a certificate or another employee managed ROS previously.
If the company still needs tax registration, agree that work separately. Revenue's registration service supports both registration activity and agent-link management, but the commercial brief should identify each task. Ask what evidence will confirm registration and what evidence will confirm access, rather than accepting one vague message that everything is set up.
7. Keep the company's own credentials private
Revenue explicitly says authorised agents use their own digital certificate and ROS password. Do not email the company's certificate, password or one-time security code as an alternative to authorisation. A provider should explain its proper access and secure document-handover arrangements before receiving sensitive information.
If someone unexpectedly asks you to approve a link, verify the request with the firm through a known contact. Do not approve unfamiliar access because a message mentions a deadline or promises a refund. For a quote, begin with a short description of the work; the first enquiry is not the place for login files, payroll records or identity documents.
8. Approval does not transfer every responsibility to the accountant
Revenue says taxpayers remain responsible for claims, declarations and returns made on their behalf. Authorisation is therefore a reason to establish a review process, not to stop asking what has been submitted. Agree how draft figures, unresolved questions, payment instructions and filing evidence will be communicated.
For each assignment, keep a simple completion record: taxpayer, tax type, period, preparer, approval and submission evidence. Ask who monitors Revenue correspondence afterwards. Do not confuse an invoice for accounting fees, a signed engagement or an access acknowledgement with evidence that a particular return has been filed.
Separate Revenue access from CRO work as well. If the engagement includes annual accounts or the B1 annual return, identify those deliverables explicitly. The company should know which person is doing each task and when information is needed, even where one firm offers several services.
9. Remove an unwanted agent link, not the tax registration
Revenue's customer ROS guide distinguishes Remove Agent Link from Cease Registration. Ending an adviser's access is not the same action as deregistering the company for a tax. Do not choose cessation simply to replace an accountant. Confirm the intended access change and check the resulting record.
Tell Revenue when an agent stops acting; Revenue warns that otherwise access can continue. Coordinate unfinished work before removing permissions, without leaving unwanted access in place indefinitely. For the wider transfer of ledgers, software, records and responsibilities, use the linked accountant-handover guide rather than treating an agent link as the whole transition.
10. Before-filing onboarding checklist
Use this as a coordination record with the adviser, not as a substitute for an actual Revenue acknowledgement or a signed engagement.
- Identify the company and the correct tax reference through secure onboarding.
- Separate company assignments from each director's personal tax work.
- Agree the tax types, periods, deadlines and named approval contact.
- Verify the adviser identity and review each requested link.
- Check the request status and retain the approval confirmation.
- Have the agent confirm usable access before relying on it for filing.
- Assign record delivery, draft review, payment arrangements and submission evidence.
- Review redundant links without accidentally ceasing a tax registration.
11. Arrange accounting support with a clear onboarding scope
StartCompany.ie's accounting service connects businesses with an accountant for their requirements. Explain whether you need a first company accountant, additional tax work or help with an incomplete onboarding process. Describe the next filing and the records available, without including passwords or a bundle of confidential documents in the general enquiry.
Ask the proposed adviser whether agent-link assistance, tax registration, bookkeeping, accounts and each return can be provided and are included. Accountant matching does not itself appoint a tax agent or approve a Revenue link. Request the written scope, availability and total payable before relying on a start date. No service enquiry guarantees immediate access or completion before a deadline.
StartCompany.ie service
Accountant Services in Ireland
Official information and next steps
Primary Revenue guidance checked on 31 October 2026. The public e-linking walkthrough is dated 12 October 2026; the linked e-linking manual was updated in March 2026. Interface labels, eligibility and processes may change. This is general onboarding information, not personalised tax, legal or account-security advice.
- Revenue: current ROS and myAccount approval walkthroughs
- Revenue TDM 37-00-04c: e-linking process
- Revenue eBrief 053/26: March 2026 update
- Revenue: appointing an agent for a business
- Revenue: managing tax registrations and agent links in ROS
- Revenue: agents use their own certificate and password
- Revenue: your responsibilities when an agent acts
- Revenue: customer ROS guide, removal versus cessation