Your first customers may be in Germany, France or the United States rather than Ireland. That raises a sensible question before you buy an Irish company formation package: does an Irish LTD need Irish customers, or is serving overseas buyers enough? The answer starts with what the proposed company will actually do and where it will do it.
This guide is for founders considering a new ordinary Irish LTD, including non-residents. It separates the customer market from the proposed Irish activity, administration, registered office and director arrangements. It is a pre-order decision guide, not an individual eligibility opinion, a cross-border tax plan or a promise that an application will be accepted.
1. Ask where the activity happens, not just where buyers live
The practical reading of section 18 is that an overseas customer list is neither an automatic rejection nor a substitute for the Irish-activity assessment. The provision concerns proposed activity in Ireland. Do not turn that into an invented requirement to acquire an Irish customer before incorporation, or a guarantee that any international business qualifies.
CRO guidance uses a broad meaning of activity, including holding, acquiring or disposing of property. It would therefore also be wrong to insist that every applicant must employ Irish staff, manufacture products or rent an operating office. The proposed facts and the appropriate legal assessment matter.
Write down what will happen in Ireland, who will carry it out and where. Distinguish an intended arrangement from one already in place. If your only explanation is that an Irish company looks attractive to foreign buyers, discuss the actual operating proposal with the presenter before paying for a routine formation.
2. Separate four locations in your formation brief
A customer address, a work location and a company contact address answer different questions. A founder can make a plausible commercial plan confusing by copying the same convenient address into every field. Prepare a short location schedule instead.
Section 22 treats the registered office, proposed activity locations in the State and normal central administration as distinct particulars. It expressly contemplates central administration being outside the State. That filing distinction is not a tax ruling or permission to misdescribe where the business is run.
| Location | What to explain |
|---|---|
| Customer market | Who buys and where the customers are located |
| Irish activity | What will happen in Ireland and at which proposed places |
| Central administration | Where the company will normally be administered |
| Registered office | The Irish address for official communications and notices |
3. Three examples: the same overseas buyers, different facts
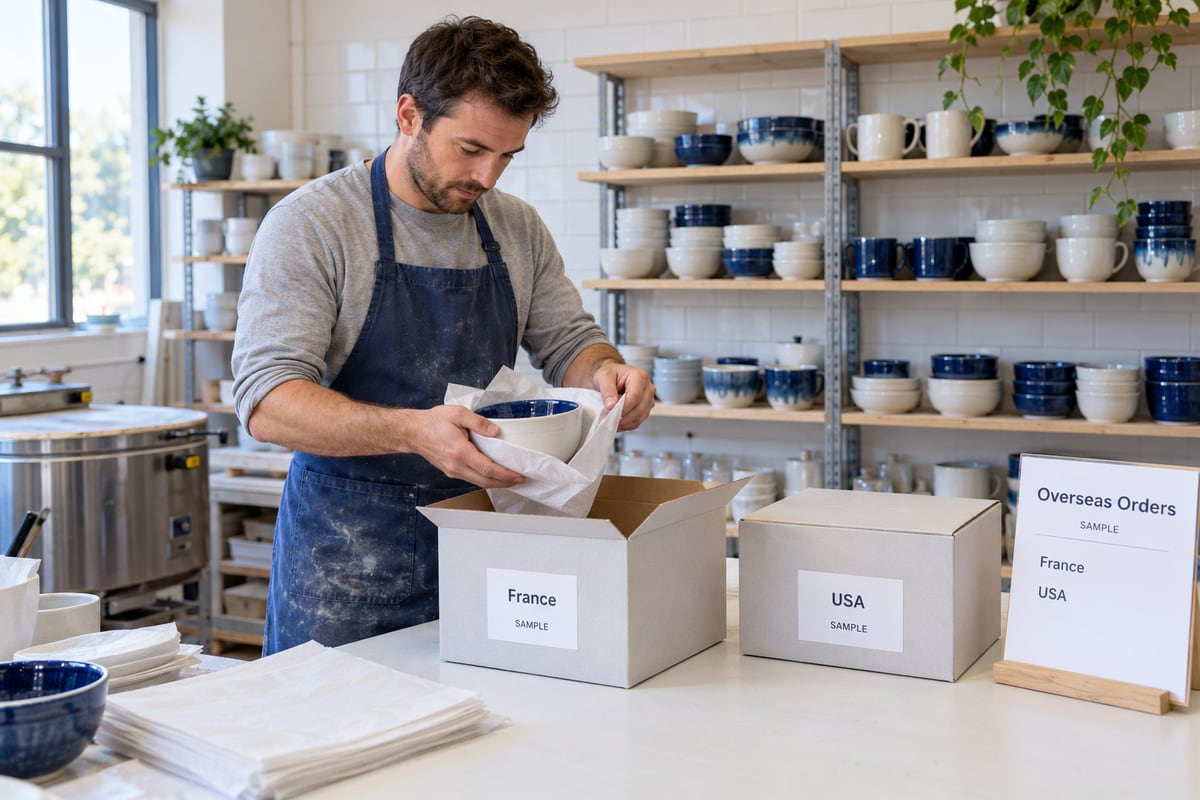
Consider a fictional ceramics business. Its owner makes and packs products in a studio in Ireland, with the initial orders going to France and the USA. The overseas buyers do not erase the studio activity. The formation brief should describe the proposed company's production and fulfilment, not merely say international sales.
Now consider a fictional services business. Its team proposes to deliver work from Ireland to business clients abroad, while a founder handles some administration overseas. Identify the people, work and locations separately. The adviser needs the supply model and actual responsibilities, not an assumption that a foreign invoice moves the service delivery abroad.
Finally, consider a founder who lives abroad, does all the work abroad and makes all decisions abroad, with only a proposed Irish mail subscription. There may be important unanswered questions about the Irish activity and the foreign position. Do not add an imaginary Irish customer, employee or workspace to make the application look easier.
These examples illustrate how to organise a discussion, not three pre-approved application categories. No particular studio, contractor agreement or address document is a universal acceptance ticket. If a proposed arrangement is unusual or incomplete, ask what assessment is needed before agreeing a filing date.
4. Give the presenter an honest activity description
CRO's activity guidance calls for the general nature and relevant classification, proposed Irish activity addresses and the central-administration address. Where multiple activities are intended, its declaration concerns the principal intended activity in the State. Use the linked NACE guide for the separate classification exercise.
A useful brief explains the product or service, who delivers it and the intended operating sequence. Separate the company's future work from an existing sole trade or foreign business. Incorporating a new entity does not automatically transfer contracts, stock, intellectual property or employees into it.
Before authorising filing, compare the final wording with your brief. Ask about an unexpected address or activity rather than approving it because it sounds professional. CRO warns about materially false or misleading declarations. Do not accept invented facts as a shortcut, and do not send private customer contracts through a public enquiry form.
5. A registered office is not automatically your workplace
Section 50 requires a registered office in the State for communications and notices. It does not say that purchasing mail handling creates manufacturing, customer support, management or storage facilities at that address.
Check what an address arrangement actually includes: allocation to your company, use permissions and the process for official mail. Workspace, customer visits, parcel fulfilment and ordinary business correspondence are separate scope questions. Do not describe the provider's address as a working studio or staffed office unless that is genuinely the agreed arrangement.
An Irish registered office alone is not a tax-residence certificate or evidence of bank approval. Keep the formal contact address and the operating proposal accurate, even when both are in Ireland. If the company will not operate from the registered office, explain the actual activity location rather than concealing that difference.
6. Choose director arrangements independently of customer countries
Section 22 requires a bond under section 137(2) to accompany incorporation where none of the first directors is resident in an EEA state. The location of your customers is not the director-residence test. Nationality and residence should not be treated as interchangeable.
For example, a founder with overseas clients should not select the Non-Resident package solely because the buyers are abroad. Establish the proposed directors and their actual residence first, then compare the published package scope. Where no director is EEA-resident, discuss the bond route and its requirements before filing.
Do not confuse appointing a secretary with appointing a director. Ask separately about a suitable secretary, identity verification and the registered office. The formation package should match the actual officer arrangements; it should not be chosen by guessing from a customer postcode or a passport alone.
7. Incorporation and tax residence need separate analysis
Revenue states that a company incorporated in Ireland on or after 1 January 2015 is deemed Irish tax-resident unless it is treated as resident in another country under a Double Taxation Agreement. Do not replace that rule with either all Irish companies are always resident or only the directors' meeting location matters.
Foreign work, management and establishments can also require advice in the other country. Give the advisers a consistent account of where decisions, people and delivery will sit. Neither an Irish customer nor the absence of one supplies a complete answer to the cross-border position.
Tax registration is separate from CRO incorporation. Revenue's new-company process requires a CRO number; receiving the incorporation certificate does not itself complete the relevant registrations. Agree who will handle the assessment, applications and subsequent accounting before issuing invoices under a tax assumption.
8. Overseas sales do not all have the same VAT treatment
For services, Revenue's general B2B place-of-supply rule looks to the business customer's establishment, while the general B2C rule looks to the supplier's establishment. Exceptions and use-and-enjoyment rules can change the result. Foreign customer therefore does not automatically mean no Irish VAT registration, no reporting or no VAT on an invoice.
For goods, Revenue's export guidance concerns dispatch outside the EU VAT area, with zero-rating conditions and evidence of departure. An order going to France and one going to the USA should not be labelled identical VAT exports merely because both customers are outside Ireland.
Before launch, give the accountant representative transactions: the product or service, business or consumer customer, relevant establishments and the goods' actual route where applicable. Have invoice wording and reporting reviewed for that model. This is an educational warning about classification, not a tax calculation or authority to issue every overseas invoice without VAT.
9. Build this pre-order readiness pack
A one-page commercial summary can expose missing decisions before money is spent. Use it to scope the formation discussion, and provide sensitive supporting documents only through the agreed secure onboarding process.
- Describe the first product or service and who will deliver it.
- List initial customer markets and whether buyers are businesses or consumers.
- Explain the real proposed Irish activity and its intended locations.
- Identify normal central administration, including an overseas location where applicable.
- Confirm proposed directors, actual residence and the separate secretary arrangement.
- Separate the registered office requirement from workplace or fulfilment needs.
- List tax, banking, licensing and any existing-business transfer questions for separate advice.
- Agree included formation work, outstanding decisions and the total payable before ordering.
10. Compare packages when the operating proposal is clear
StartCompany.ie's published packages let you compare Irish LTD formation work against the services you actually need. Review the current inclusions for incorporation preparation, filing, documents and any listed additional support. Check the specific bond package where that route is required; do not assume every overseas founder needs the same combination.
A formation order does not create an Irish operating presence for you. It does not automatically include cross-border tax advice, commercial premises, contract transfers, a banking decision or immigration permission. Ask about extra work and its availability instead of treating the package as a complete international relocation service.
If the Irish activity is still unclear, contact the team before placing an order. A useful enquiry explains the proposed business and asks which facts or specialist advice must be settled first. Once the scope is agreed, confirm the total payable and the remaining founder tasks. No service purchase guarantees CRO acceptance, a particular tax outcome, banking access or permission to live or work in Ireland.
StartCompany.ie service
Compare Irish company formation packages
Official information and next steps
Official sources were checked on 1 November 2026. The customer-location distinction is a practical reading of the cited rules, not a CRO decision on an individual proposal. Examples are fictional; obtain advice on the actual Irish and foreign legal and tax facts.
- CRO: activity in the State and Form A1
- Companies Act 2014, section 18: activity in the State
- Companies Act 2014, section 22: incorporation particulars
- Companies Act 2014, section 50: registered office
- Revenue: company residency rules
- Revenue: general place-of-supply rules for services
- Revenue: VAT and exports of goods
- Revenue: registering a new company for tax